Chapter 3
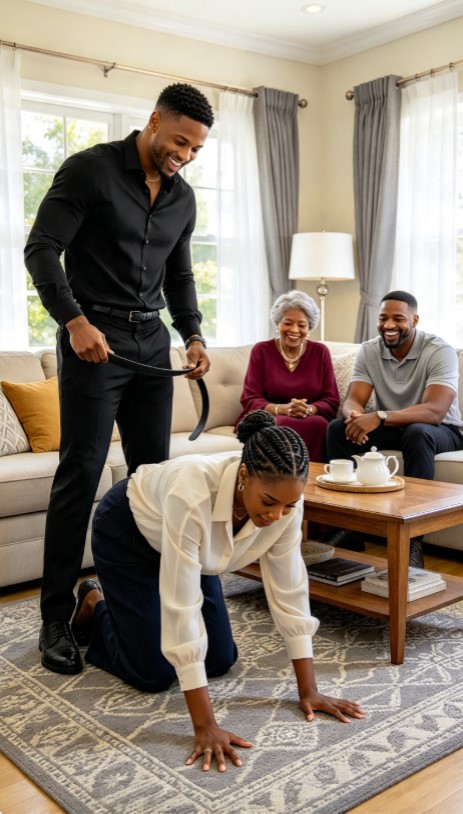
Naomi had never imagined she would need an incident number to ask questions about her own house.
In Mrs. Reid's guest room, morning light fell across the blue authorization page. At the top was the name of a local credit union. Below the address was a line describing "owner consent for preliminary equity review." That phrase sounded harmless until Naomi read the section authorizing communication with third parties about available collateral.
She hadn't requested a home-equity loan. She hadn't contacted the credit union. And she certainly hadn't authorized Daniel, whose name appeared in the footer as "referral contact," to discuss her property.
She called the credit union's published number, not the one printed on the suspicious form. After verifying her identity, a service representative transferred her to the lending department. Naomi explained that somebody might be trying to start an application in her name.
The representative was careful. She could confirm there was an inquiry associated with Naomi's address, but not discuss another person's account. She offered to connect Naomi with the fraud team and advised her to submit a written dispute with copies of the page and police incident number.
"Has money gone out?" Naomi asked.
"I can't make that determination from this screen," the woman said. "But we're flagging your report now."
Not a victory. Not an answer. Still, for the first time since the belt clicked against Marcus's ring, Naomi had taken a step nobody in that living room controlled.
She opened the online banking app and checked each balance, then checked again because she didn't trust the numbers to remain unchanged. Her regular checking account looked untouched, but she understood the proposed loan was a separate problem. An application could exist without money having moved. What frightened her was the thought of waking up years later to discover a lien had appeared because she'd failed to act now.
Mrs. Reid found her staring at the screen and suggested a five-minute walk. They went no farther than the mailbox. Naomi could see the oak tree outside her own bedroom across the street. "I keep thinking I should go home and ask him one more time," she said. Mrs. Reid replied, "A question is allowed to have an answer that isn't given by the person who scared you." Naomi carried that sentence back inside.
She contacted the county property records office online. The deed showed what she had always known: the house belonged to Naomi Carter alone. Loretta had transferred it to her daughter years before Naomi married Marcus. The current public record showed no new deed transferring ownership.
She saved the document. Then she photographed the scars the rough rug had left on her palms.
Marcus began calling at nine.
First came an apology: I shouldn't have scared you. Then: You're embarrassing the family. At ten thirty: Daniel says you're making dangerous accusations. At eleven: Mom's blood pressure is up because of this.
Naomi put the phone on silent and kept every message.
Mrs. Reid brought toast into the guest room. "You don't have to read them as they come," she said.
"He knows exactly how to pull me back," Naomi admitted. "First he apologizes. Then I'm the one hurting everyone."
"Then give yourself time before answering."
Naomi opened a notes document and began listing what she knew. The family-planning folder had appeared the previous evening. Daniel had brought it. Evelyn had arranged the tea service on top of its contents. Marcus had refused to show Naomi the pages. And the unauthorized signature carried tomorrow's date.
At noon, the credit union's fraud specialist called back. She confirmed that a preliminary application had been submitted for a secured line of credit, subject to underwriting, identity checks, appraisal, and owner verification. It was not an approved or funded loan.
"What's the amount?" Naomi asked.
The specialist paused to confirm what she was allowed to disclose to the reported property owner. "The requested limit is one hundred and thirty-two thousand dollars."
Naomi gripped the edge of the desk. Her annual salary was less than half that. The home was nearly paid off because her mother had spent decades working two jobs to keep it.
"I never applied."
"We've marked that clearly. Please send your signed statement. You may also want to consider a credit freeze and consult an attorney about any additional documents you've received."
Naomi emailed the documents and followed the instructions to place freezes with the major credit bureaus. Each step required another password, another security question, another deliberate breath.
Then she zoomed in on the bottom of the blue page. A tiny tracking code appeared beside Daniel's printed name: DC-0417. Beneath it was a label Naomi hadn't noticed before.
SOURCE: FAMILY COUNSELING INTAKE.
For three months Marcus had been urging her to attend family counseling. Two weeks earlier, she had signed what he called an intake form on his tablet while cooking dinner.
May you like
She could still hear him saying, "It's just permission to schedule the appointment."
Had that innocent-looking consent been used to build an application for a loan she never wanted?